Digital Asset Clearing Center is building the infrastructure needed to connect Hong Kong’s tokenised bonds, stablecoins and cross-border RMB settlement systems.
Connecting Blockchain to Banking
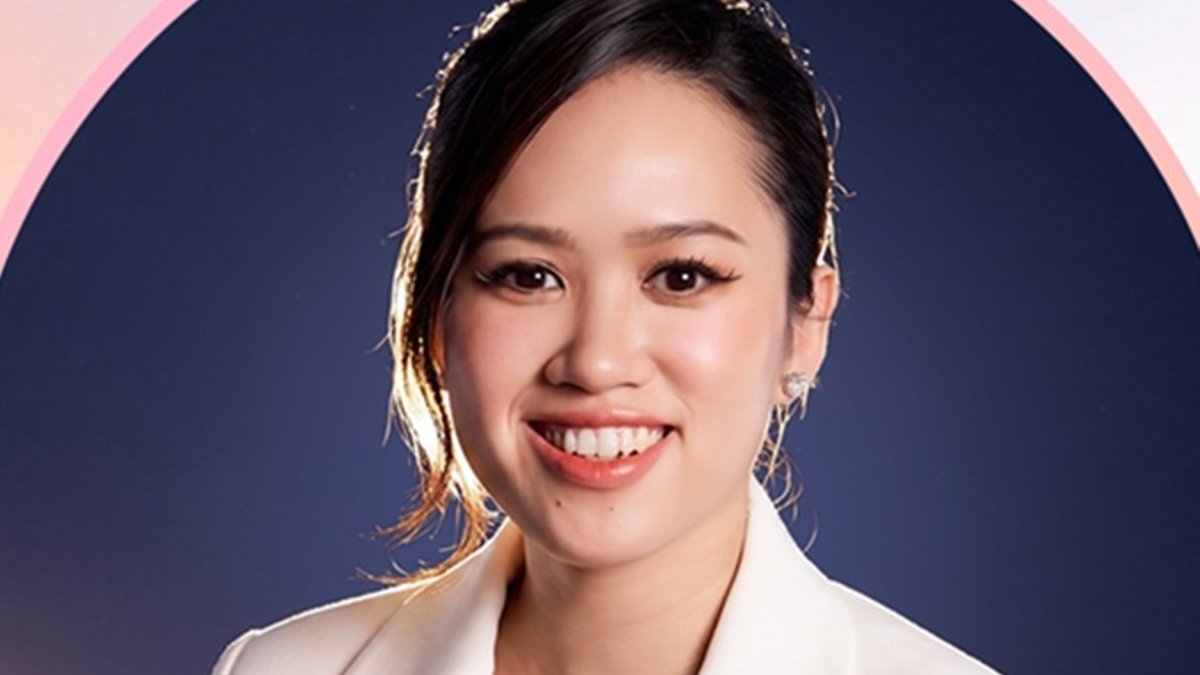
DACC is positioning itself as a Hong Kong-headquartered infrastructure company for the next phase of regulated digital finance. The company focuses on digital asset clearing, settlement and infrastructure. Co-Founder and Chair Serra Wei believes the future of finance involves connecting blockchain-based assets with the payment systems, custody structures and compliance frameworks that institutions already use.
“We are all agreeing that the future of assets and financial products will be more and more on blockchain,” Wei said. “But every region has its uniqueness and killer products in how the ecosystem will grow.”
DACC’s Hong Kong focus emerged around four years ago as the city made a stronger policy push into Web3, tokenisation and digital asset infrastructure. Wei’s background reflects the bridge her company is trying to build. She started her career in traditional finance at Goldman Sachs, studied at Stanford Graduate School of Business, and later moved into venture capital investing in digital assets and tokens from as early as 2017.
Why Hong Kong’s Strategy Matters
Hong Kong is positioning itself as one of Asia’s most important regulated digital asset hubs. Wei sees the city’s role as distinct from markets that are primarily focused on crypto trading. Hong Kong’s advantage lies in its existing strength as an international financial centre and bond issuance hub, combined with its connection to mainland China and cross-border RMB flows.
“The way we see it in Hong Kong is that Hong Kong plays a unique role,” Wei said. “They are focusing on tokenisation.”
Wei believes the most important product in Hong Kong is the digital bond. The Hong Kong government has already been active in government digital bond issuance, issuing multiple bonds and continuing to view this as part of its broader market development strategy. She also referred to policy discussions around tokenising existing Hong Kong government bonds and creating retail participation quotas.
Digital bonds could become one of the first mainstream institutional use cases for blockchain in capital markets. For issuers, tokenised bonds can potentially improve settlement efficiency, transparency and distribution. For investors, they could open access to new digital financial products. For Hong Kong, they reinforce the city’s ambition to remain a leading capital market while also becoming a Web3 finance hub.
Related: Malaysia Becomes Trusted ASEAN Trade Hub
Solving the Infrastructure Problem
The challenge is that tokenised assets do not exist in isolation. A bond may be issued on a blockchain, but payment may still need to move through off-chain systems such as SWIFT, CIPS or digital RMB infrastructure. Stablecoins may operate on public blockchains, while tokenised deposits may sit on private chains. Banks and broker-dealers still rely on existing systems, compliance workflows and customer interfaces.
DACC is trying to solve this fragmentation. The company calls this solution DACC TransFusion. The platform is designed to support cross-chain and cross-payment settlement across public blockchains, private blockchains, stablecoins, SWIFT, CIPS and digital RMB.
“When you have assets that are on the blockchain wanting to settle with money, when the payment system is off the blockchain, we provide this payment gateway,” Wei said.
In simple terms, DACC is building the connective layer between tokenised assets and multiple forms of money. That matters because the future of digital finance is unlikely to be one single rail. It will be a multi-rail system where blockchain assets, stablecoins, tokenised deposits, digital RMB, traditional payment systems and bank infrastructure coexist.
Speeding Up Settlement
One of the clearest business benefits of DACC’s infrastructure is settlement speed. Traditional cross-border transactions through SWIFT can take three to five days. Wei said DACC’s model, which links blockchain asset finality with payment-system finality, can dramatically compress that timeline.
“For cross-border transactions, people sometimes still complain that SWIFT transactions can take three to five days,” she said. “With this new way of settlement, we can substantially reduce the cross-border payment time from three to five days to seconds.”
For banks, broker-dealers, asset managers and trading platforms, that has major implications. Faster settlement can reduce counterparty risk, improve liquidity, free up capital and make cross-border products more efficient. In digital bond markets, where issuers and investors may be located across different jurisdictions, settlement efficiency can become a key competitive advantage.
DACC’s strategy is not to bypass existing banks and broker-dealers. It is to integrate with them. Wei said one of DACC’s pilots involves taking digital bonds issued on private blockchains and making them available for retail distribution. The goal is to allow digital bonds and tokenised assets to be accessed through existing financial institutions, including banks and broker-dealers in Hong Kong, Central Asia, Southeast Asia and other international markets.
Related: Philippines salt output reaches 199k tonnes BFAR reports
Three of the public companies on DACC’s cap table are large Web2 fintech companies in Asia. One of them, TTL, has more than 50% market share among Hong Kong banks and broker-dealers. That integration allows DACC to connect digital asset infrastructure with systems institutions already use.
“From the banks’ and broker-dealers’ perspective, it is seamless,” Wei said. “They do not really feel the difference because they are still using existing broker-dealer systems for trading. But now they are able to access digital bonds, tokenised assets and receive stablecoins.”
Wei said stablecoins are increasingly being discussed not merely as crypto instruments, but as payment and settlement rails inside regulated financial systems. In Hong Kong, she expects bank-issued stablecoins to support use cases within the banking ecosystem.
“There are two banks that are issuing stablecoins in Hong Kong, and I think there are going to be different use cases around the banking ecosystem,” she said. “It is this ability where money can move more seamlessly.”
DACC already supports stablecoin inflows and outflows for trading, connected to existing banks and broker-dealer systems. The important distinction is that stablecoins, in DACC’s model, are part of a regulated financial infrastructure stack. They are not treated as separate from banking. Instead, they are one form of money among several forms that may be used for settlement.
Regulation and Custody
For institutional digital assets, compliance is not optional. Wei said financial institutions operate through regulated policies and procedures, and DACC has built compliance and risk management into its activities and business divisions.
“When dealing with financial institutions, it is really about compliance and policy procedures,” she said. “Every activity or every division within DACC has embedded compliance and risk.”
That includes custody controls such as checks and balances, multi-approval processes, backups, segregation of assets and segregation of duties. DACC is also in the process of becoming a regulated custodian through an upcoming SFC licence in Hong Kong.
Related: DoH reports 70 percent drop in COVID cases
For Wei, this is a necessary step if digital asset infrastructure is to gain the trust of clients and regulators. This is where the institutional digital asset market differs from earlier crypto cycles. Banks and regulated financial institutions require auditability, compliance controls, asset segregation, operational resilience and regulatory clarity before they can scale adoption.
Looking Ahead
DACC’s Hong Kong location also gives the company a strategic position in cross-border RMB settlement. Wei said China’s position as the world’s second-largest economy means global financial institutions are increasingly required to hold and engage with RMB. If tokenisation and digital bonds continue to grow, cross-border RMB settlement could become a major use case.
“If tokenisation and digital bonds continue to increase, that is a great use case for cross-border RMB,” she said. “We are seeing the trend, and we are supported by government initiatives and market demand.”
This links directly to Hong Kong’s broader role as a connector between mainland China and international capital markets. DACC’s infrastructure is designed to support multiple payment systems, including CIPS, SWIFT and digital RMB. That positions the company to participate in a future where assets may be tokenised, but settlement could involve several forms of money and payment rails.
Wei also expects artificial intelligence to become part of DACC’s business and the wider digital finance ecosystem. “AI is the future for whatever industry, and for our industry as well,” she said. She said DACC is focused on AI and is exploring acquisition activity involving fintech companies in AI.
Looking ahead, Wei said DACC wants to become an open financial market infrastructure in Hong Kong, connecting Hong Kong and mainland China while helping grow the tokenisation ecosystem and support RMB internationalisation.
“DACC is uniquely positioned as the open financial market infrastructure in Hong Kong and connecting Hong Kong and Chinese mainland,” she said. “We are aspiring to grow this tokenisation ecosystem along with promoting RMB internationalisation.”