Manufacturing activity across Southeast Asia picked up pace in July, signaling a potential rebound for the industrial sector. The region’s Purchasing Managers’ Index climbed to 52.8, a notable increase from 50.5 in June. This marks the strongest improvement in operating conditions seen in five months. The data suggests the sector is finally recovering from a sluggish second quarter that dampened expectations earlier this year.
Production Gains Drive Recovery
The rise in the S&P Global ASEAN Manufacturing PMI was largely driven by faster growth in new orders and output. New orders grew at their quickest rate since February. Manufacturers responded by ramping up production, which expanded at the fastest rate in five months. Amongst the seven monitored economies, all except Myanmar recorded stronger operating conditions. This broad-based recovery indicates that the slowdown seen earlier in the year is reversing course as client demand returns.
Related: Digital Dollar Systems Gain Global Traction
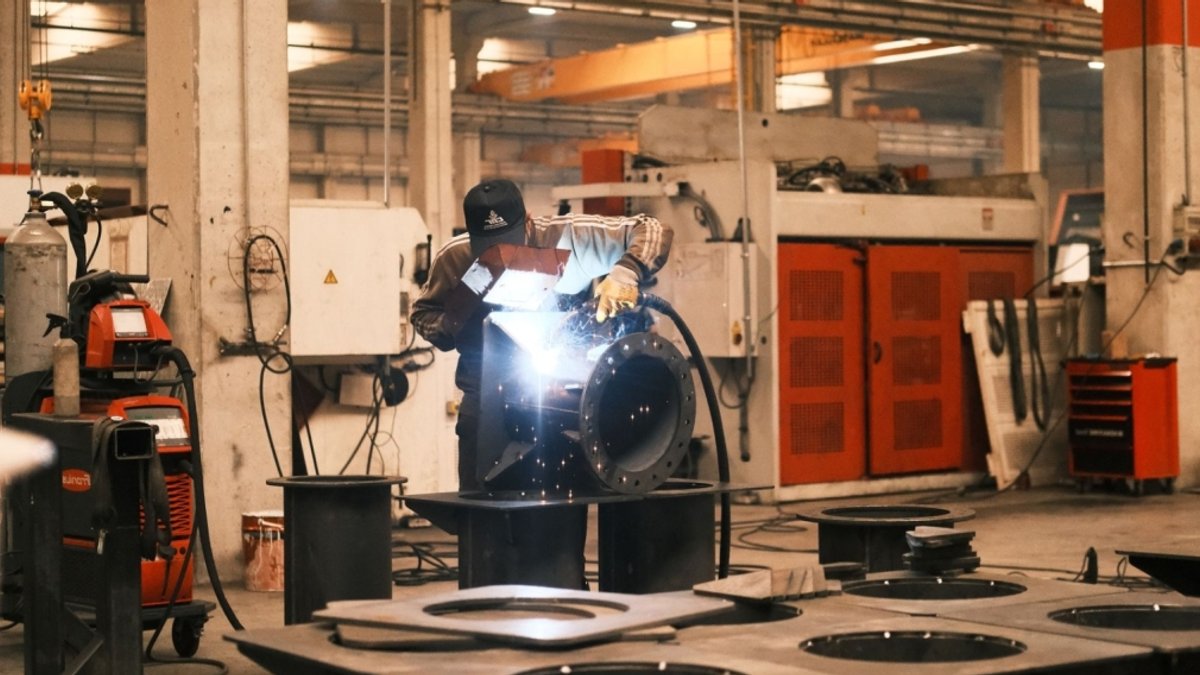
To meet this rising demand, firms increased their purchasing activity noticeably. Employment levels also rose, marking the first hiring increase since March. However, the hiring pace did not fully keep up with surging production requirements. This mismatch regarding labor and demand caused work backlogs to grow at the fastest rate since October. As factories try to clear these accumulated orders, the pressure on existing workflows will likely test the efficiency of current operations.
The sudden uptick suggests factories are maneuvering through previous disruptions, though the sustainability of this momentum remains to be seen. If global demand continues to stabilize without new external shocks, the region could see a steady return to the record levels observed earlier in the year. However, relying solely on current order books might not be enough if supply chain constraints tighten further.
Cost Pressures and Future Outlook
Price pressures have eased slightly since a spike in April, but input costs are still rising sharply. Manufacturers are passing these costs on to customers through higher selling prices. This transfer of expenses to the end buyer is a necessary step to protect margins, but it carries risks. Maryam Baluch, an economist at S&P Global Market Intelligence, noted the sector seems to have moved past a softer patch that dragged down performance.
Related: ZUS Coffee adjusts defense secures back-to-back wins
“The ASEAN manufacturing sector appears to have moved past the softer patch seen between March and June,” Baluch said. She explained that activity during those months was heavily affected by the ongoing conflict in the Middle East. While performance is now on par with the start of the year, it still sits below the record high reached in February. The road to recovery appears to be gaining traction.
Supply chains faced some strain, as suppliers’ delivery times lengthened moderately during the month. Despite these delays, manufacturers increased their stock of purchases for the first time in four months. This inventory build-up suggests firms are anticipating further growth and want to avoid shortages. Business confidence has strengthened to its highest level since April 2023. Firms expect output to rise over the coming year as demand conditions improve.